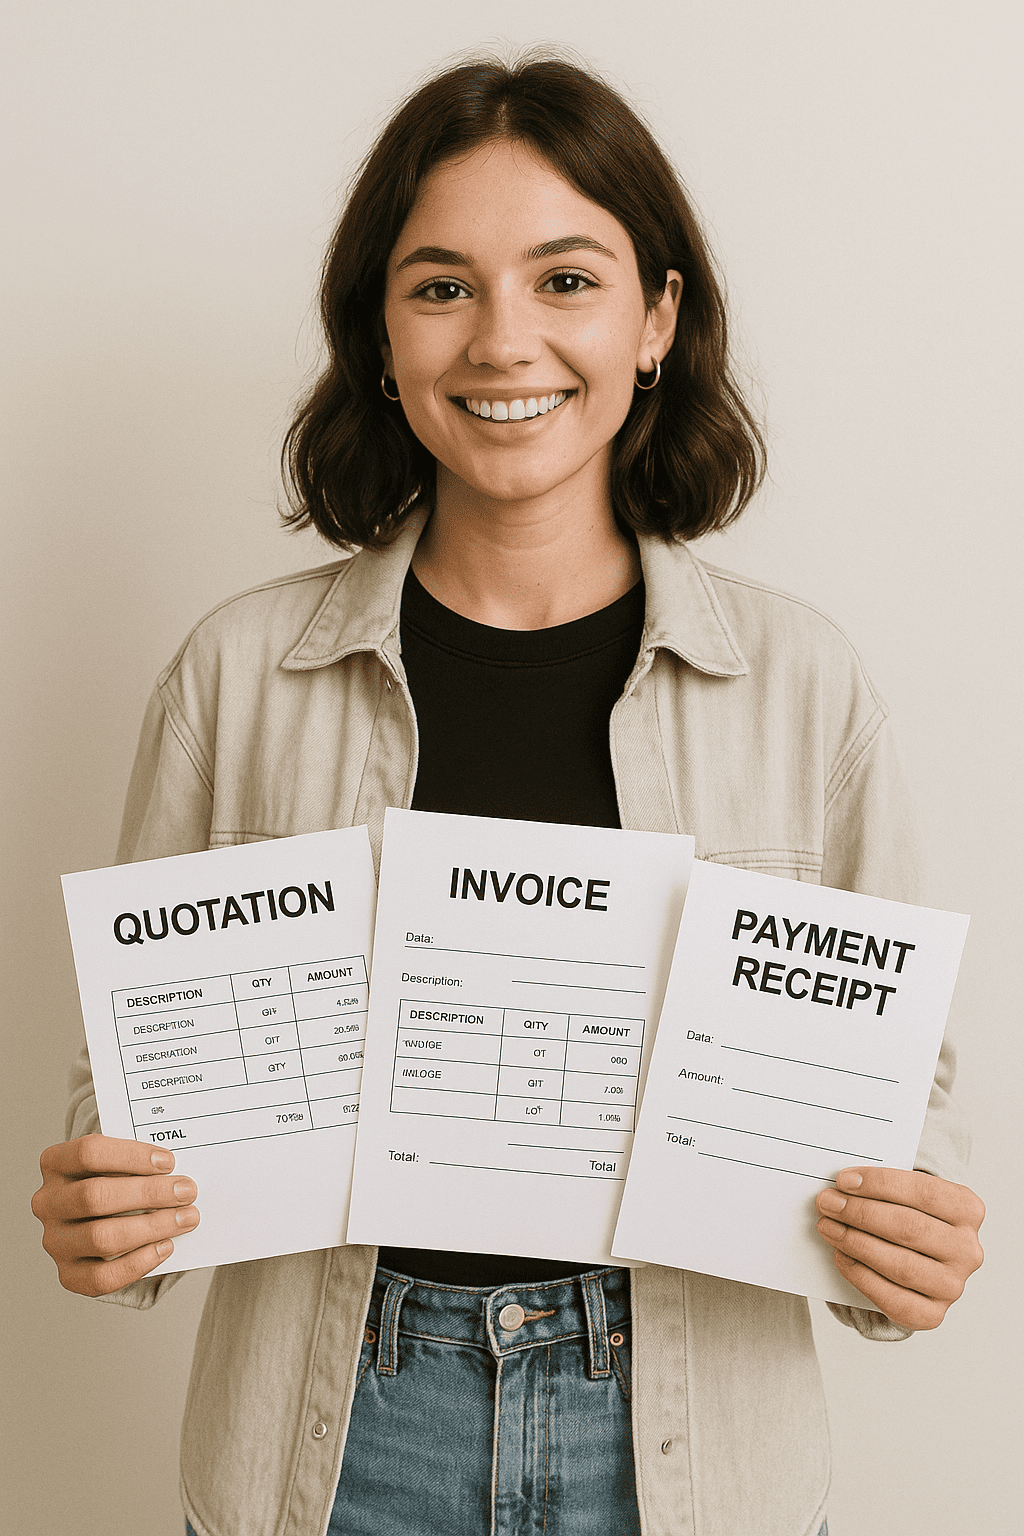
Stop Losing Money: Common Pricing Errors in Quotations That Cost Your Business

The Silent Profit Killer: Why Accurate Quoting is Critical

For many businesses, the quotation is the handshake before the deal—a formal promise of value and price. Yet, this critical document is often a source of significant financial loss. Common pricing errors in quotations, ranging from simple calculation mistakes to strategic missteps, erode profit margins and damage customer trust. Understanding where these errors occur is the first step toward safeguarding your bottom line.

Data Entry and Calculation Mistakes: The Manual Risk

One of the most frequent and preventable errors is basic manual calculation failure. Whether inputting the wrong unit price, miscalculating quantities, or applying incorrect formulas for bulk discounts, data entry errors can dramatically undervalue your service or product. When sales teams rely on complex spreadsheets without proper validation, human error inevitably creeps in. A slight miscalculation on a high-volume quote can translate into thousands of dollars in lost revenue, turning a potentially profitable deal into a loss leader. Implementing CPQ (Configure, Price, Quote) software can automate these complex calculations, drastically reducing the risk associated with manual data handling.

Ignoring Overhead and Indirect Expenses

Many businesses focus solely on direct costs (materials, labor) when formulating a quote, neglecting the essential but less tangible indirect expenses. Overhead costs—such as administrative salaries, rent, utilities, insurance, and marketing—must be correctly allocated and included in the final price to ensure true profitability. Failing to bake in a realistic overhead percentage means that while the deal might cover the production cost, the business is effectively operating at a loss concerning its total operational expenditures. A robust quoting process requires a clear, standardized methodology for allocating these indirect costs across all projects or products.

Failing to Account for Scope Creep

In service industries, particularly consulting and development, “scope creep” is a pervasive issue. A quotation sets the boundary for the work, but clients often request minor additions or changes that seem small individually but accumulate over time. If the original quote fails to clearly define boundaries and establish procedures for charging for revisions or additions, the business absorbs those extra costs. Every quote must include provisions for change orders and detailed documentation outlining what is, and is not, included in the quoted price. This protects profitability and manages client expectations effectively.

Strategic Discounting Errors and Margin Erosion

Discounts are a powerful sales tool, but reckless application destroys margins. Common mistakes include offering excessive discounts to secure a deal, failing to track the aggregated impact of multiple small discounts, or granting discounts without understanding the true minimum acceptable margin. Before a discount is applied, sales teams must have clear guidelines defining authorization levels and the measurable ROI of the concession (e.g., securing a long-term contract or high-volume order). If a discount simply moves the product or service faster without strategic value, the business is sacrificing profit unnecessarily. Precision in pricing is not just about avoiding undercharging; it’s about strategically maximizing every opportunity while ensuring long-term financial health. Reviewing and standardizing your quoting procedures is essential to stop these profit leaks today.
Tagged : / / / / / /

5 Common Invoicing Mistakes That Delay Payments and How to Avoid Them

Introduction: The Cost of Clerical Errors

For small businesses and freelancers, cash flow is king. Unfortunately, many payment delays aren’t caused by reluctance to pay, but by simple, preventable errors on the invoice itself. A flawed invoice is often sent back for correction, kicking the payment cycle back weeks. Understanding and eliminating these common invoicing mistakes is crucial for maintaining healthy financial operations.

1. Missing or Inaccurate Payer Information

One of the most frequent errors is failing to include complete and correct information. This includes the legal business name of the client, the full address, and, crucially, the specific contact person or department responsible for accounts payable (AP). If the invoice lands on the wrong desk, the payment process stalls immediately. Always verify the required ‘Bill To’ details before issuing the invoice, especially for new clients.

2. Vague or Non-Existent Payment Terms

If your invoice simply states “Due,” it leaves too much open to interpretation. Clear payment terms—such as “Net 30,” “Due Upon Receipt,” or specific late payment penalties—are essential for establishing expectations. Without defined terms, the client has no official deadline, making follow-up difficult and delaying settlement. Ensure your terms are unambiguous and legally sound.

3. Forgetting the Purchase Order (PO) Number

In B2B environments, especially with large corporations, payment processing is often automated using Purchase Order (PO) numbers. If the PO number required by the client is missing or incorrect, the invoice cannot be matched to the original service agreement and will be rejected automatically by the AP system. Always request the required PO number at the time the work is commissioned and place it prominently on the invoice.

4. Calculation Errors and Unclear Itemization

Trust is undermined quickly by invoices that contain mathematical mistakes or confusing line items. If a client spots an error in the totals or can’t decipher what they are being charged for, they are obligated to pause payment for clarification. Use professional invoicing software to eliminate manual calculation risks, and ensure every service or product is clearly described, dated, and priced separately.

5. Incorrect Submission Method

Many organizations require invoices to be submitted via a specific portal, dedicated email address (e.g., [email protected]), or even physical mail to a central lockbox. Submitting the invoice to your usual project manager or a personal email address, even if well-intentioned, often results in the invoice being lost or significantly delayed as it waits to be routed to the correct department. Confirm the client’s preferred submission protocol every time.

Conclusion: Streamline Your Process, Accelerate Your Cash Flow

Preventing payment delays starts with meticulous attention to detail during the invoicing process. By utilizing standardized templates, double-checking client requirements (especially PO numbers and submission methods), and maintaining clear, professional communication, you significantly reduce the risk of clerical errors. Investing a few extra minutes in accuracy will ensure your business receives payment on time, every time.

Tagged : / / / / /

The Critical Connection: How Accurate Invoices Improve Cash Flow for Small Businesses

Introduction: The Cash Flow Challenge

For small businesses, consistent cash flow is the lifeblood that determines survival and growth. While securing sales is essential, the efficiency of your invoicing process is often the overlooked factor dictating when that revenue actually hits your bank account. Inaccurate invoices are a hidden menace, responsible for frustrating delays, costly disputes, and, ultimately, crippling gaps in cash flow management.

The Direct Link: Accuracy Equals Speed

Every small business owner knows that a client receiving an invoice with an error—whether it’s an incorrect service description, the wrong billing address, or a missing purchase order (PO) number—will pause payment. These seemingly minor mistakes force the client’s accounting department to flag the document, initiating a back-and-forth communication loop that can delay payment by days or even weeks. In the fast-paced world of small business finance, a week’s delay in receiving a large payment can be the difference between making payroll and facing a crisis. Accuracy ensures the invoice sails smoothly through the client’s system the first time, leading to faster payment cycles and predictable cash inflow.

Streamlining the Payment Process with Detail

An accurate invoice is not just about having the right numbers; it’s about providing complete clarity. Professionalism and detail foster trust and minimize questions. Key elements that must be flawless include: the clear breakdown of goods or services provided, agreed-upon pricing, the official invoice date, a visible and accurate due date, and unambiguous payment terms (e.g., Net 30). Furthermore, ensure all necessary recipient details, like tax identification numbers or relevant project codes, are included. By making the payment process frictionless, you drastically reduce the excuses and administrative hurdles that typically slow down remuneration.

Minimizing Disputes and Write-offs

Inaccurate billing is a primary catalyst for client disputes. If the amount on the invoice doesn’t match the initial quote or the quality of service is poorly documented, clients are likely to challenge the bill, potentially leading to lengthy negotiations, partial payments, or even refusal to pay the full amount. This financial friction drains resources, demanding valuable time spent rectifying errors instead of focusing on core business activities. Consistent accuracy, backed by meticulous records, establishes credibility and legally solidifies your right to payment, helping you avoid costly write-offs that erode profitability and severely damage cash flow.

Leveraging Technology for Precision

Manual invoicing is inherently prone to human error. Modern small businesses should leverage dedicated accounting and invoicing software (like QuickBooks, Xero, or specialized CRM tools) to automate the process. These systems automatically pull accurate client data, calculate sales tax, track billable hours, and ensure compliance. Automation not only saves time but virtually eliminates the typographical and computational errors that are so detrimental to cash flow. Implementing a systemized approach is an investment that pays for itself through accelerated payments and improved financial stability.

Conclusion: Paving the Way for Stability

For small businesses, cash flow optimization starts at the fundamental level of documentation. Accurate invoicing is more than a clerical task; it is a critical strategic component of financial management. By adopting meticulous attention to detail and leveraging technological aids, you transition from reactive chasing of overdue funds to proactive management, ensuring a steady, predictable cash flow stream that supports sustained operation and fuels future growth.

Tagged : / / / / / /

The Complete History: The Evolution of Invoicing from Paper Bills to Smart Digital Systems

The Silent Revolution in Finance: Why Paper Bills Are Extinct

For centuries, the exchange of goods and services relied on cumbersome physical documents. Before the era of instantaneous financial transactions, the invoice—a simple record of a debt—was a critical piece of paper, often stored in dusty ledgers and sent via slow postal services. Today, finance departments worldwide are witnessing one of the fastest digital transformations, moving from these error-prone paper trails to sophisticated, automated digital invoicing systems. This evolution is not just about convenience; it’s about establishing a foundation for real-time commerce and enhanced financial security.

The Dawn of Commerce: The Limitations of the Paper Trail

In the pre-digital age, the workflow surrounding an invoice was manual and multi-layered. Businesses had to print, fold, stamp, and mail bills, leading to significant delays in payment cycles. Furthermore, manual data entry upon receipt was the standard, a process infamous for human error, leading to misapplied funds, disputes, and lengthy reconciliation periods. Storing physical documents required vast archives, complicating audits and compliance checks. The paper invoice, while historically essential, became a major bottleneck in the acceleration of modern business operations.

The Transitional Phase: From Fax to Standardized PDFs

The first significant leap came with the adoption of email and digitized formats. The fax machine provided an early, albeit primitive, method of faster transmission. However, the widespread introduction of the PDF format allowed companies to send visual replicas of invoices instantly. While an improvement in speed, this phase was still transitional. A PDF invoice, though digital for transmission, still required manual intervention—someone had to open the document, read the data, and key it into the recipient’s accounting system. This semi-digital process only solved the transmission problem, leaving the critical data processing challenge intact.

Smart Invoicing: AI, Automation, and True Efficiency

The current generation of invoicing leverages true smart technology, marking the definitive end of the manual workflow. Modern e-invoicing systems utilize structured data formats (like XML or UBL) and technologies such as Electronic Data Interchange (EDI) and Application Programming Interfaces (APIs). This allows invoices to be sent directly from one accounting system to another, without human interference.

Artificial Intelligence (AI) and Machine Learning (ML) play a crucial role in modern accounts payable (AP) automation. These systems can instantly read unstructured data from legacy formats, automatically match invoices against purchase orders (PO) and goods receipts, flag discrepancies for human review, and categorize expenses. Benefits include processing times reduced from weeks to mere hours, dramatic reduction in processing costs, and near-perfect accuracy.

The Future is Real-Time and Secure

The evolution towards smart, compliant digital invoicing is central to the broader financial ecosystem. It enables real-time cash flow visibility, drastically lowers the risk of fraud inherent in paper systems, and facilitates faster payment cycles. As regulations increasingly mandate structured e-invoicing (especially in Europe and parts of Latin America), businesses that embrace full automation are gaining a significant competitive edge. The future promises even greater integration, potentially utilizing blockchain technology for immutable, instant-settlement invoicing, solidifying the paper invoice’s place as a relic of history.

Tagged : / / / / / / /

The Financial Revolution: The Essential Role of Cloud Accounting Software in Managing Quotes, Invoices, and Receipts

The Digital Transformation of Financial Administration

For modern businesses, managing the trifecta of quotes, invoices, and receipts has traditionally been a tedious, error-prone process. The filing cabinet is dead. Today, forward-thinking companies are leveraging sophisticated cloud-based tools to automate, streamline, and integrate these critical financial workflows, marking a significant step towards financial stability and operational efficiency.

Cloud accounting software moves these processes off local servers and onto secure, accessible online platforms. This shift not only eliminates the risk of data loss associated with local hardware but also provides instant, real-time access for owners, managers, and accountants, regardless of their physical location. This accessibility is crucial for rapid decision-making and remote work environments.

Streamlining the Quoting and Estimation Process

The first impression a business makes often starts with a quote. Cloud tools transform this initial touchpoint from a manual spreadsheet task into a polished, automated function. Users can instantly generate professional-looking quotes using customizable templates, ensuring brand consistency. Crucially, these tools often integrate inventory and service pricing databases, minimizing calculation errors and speeding up delivery time. Once a quote is accepted, a single click can convert it directly into an invoice, eliminating redundant data entry.

Modernizing Invoicing and Accounts Receivable

Invoicing is the heart of cash flow management. Cloud-based solutions significantly improve the speed and reliability of payment collection. Features like automated recurring invoicing are indispensable for subscription models, while integrated payment gateways (like Stripe or PayPal) allow clients to pay instantly online, drastically reducing days sales outstanding (DSO). Moreover, automated payment reminders—sent precisely when payments are due or overdue—take the emotional labor and administrative burden out of collections.

Hassle-Free Digital Receipt Management

Receipt management is arguably the most dreaded part of financial administration, yet it is vital for tax compliance and expense tracking. Cloud tools revolutionize this area using mobile apps that allow employees to capture images of physical receipts instantly. Optical Character Recognition (OCR) technology extracts key data points (vendor, amount, date) and automatically categorizes the expense. These digital receipts are securely stored in the cloud, linking directly to the relevant transaction, ensuring a pristine audit trail.

The Overarching Benefits: Accuracy, Security, and Compliance

The cumulative effect of implementing these cloud-based processes is profound. Increased accuracy stemming from automated calculations reduces costly human errors. Enhanced security, provided by encrypted servers and robust access controls, protects sensitive financial data far better than physical filing systems. Finally, maintaining digital records simplifies tax season immensely. Auditors appreciate the clear, categorized, and timestamped nature of cloud-stored documents, ensuring businesses remain fully compliant with regional and international accounting standards. Adopting these tools is no longer a luxury; it is a foundational requirement for sustainable business growth.

Tagged : / / / / / /

Essential Digital Finance Documentation Trends Every Business Must Master

The Imperative Shift to Digital Finance Documentation

The financial landscape is undergoing a rapid digital transformation, making outdated paper-based processes obsolete. For modern businesses, mastering digital finance documentation is not just about efficiency; it’s a critical component of security, regulatory compliance, and competitive advantage. Understanding the key Digital Finance Documentation Trends shaping 2024 and beyond is essential for every CEO and finance professional seeking streamlined, transparent operations.

Trend 1: Hyper-Automation and Robotics Process Automation (RPA)

One of the most impactful trends is the move towards hyper-automation in documentation handling. RPA tools are being deployed to automate repetitive, high-volume tasks such as invoice processing, expense report reconciliation, and contract drafting. This drastically reduces processing time, minimizes human errors inherent in manual data entry, and frees up finance teams to focus on strategic analysis rather than tedious administration. The immediate result is faster closing cycles and improved data accuracy, directly impacting reporting quality and decision-making.

Trend 2: Intelligent Document Processing (IDP) Powered by AI

AI and Machine Learning are revolutionizing how unstructured financial data is managed. Intelligent Document Processing (IDP) tools use AI to scan, categorize, and extract relevant data from various document formats (e.g., PDFs, images, scans) far more accurately than traditional optical character recognition (OCR) software. For instance, IDP can automatically flag anomalies in transaction documents or verify the legitimacy of supporting paperwork, significantly bolstering fraud detection efforts and ensuring robust audit trails. This shift turns mountains of documents into actionable, categorized digital assets.

Trend 3: Cloud-Native Platforms for Real-Time Access

The widespread migration to cloud-native financial platforms facilitates the central storage and management of all financial records. Cloud solutions offer unparalleled scalability, accessibility, and robust disaster recovery protocols. Real-time document access and secure collaboration across different geographic locations are now standard expectations. Furthermore, leading cloud providers incorporate advanced security features that often surpass what individual businesses can maintain on-premise, making them essential for protecting sensitive financial documentation from breaches.

Trend 4: Blockchain for Immutable Audit Trails

While still emerging, distributed ledger technology (DLT), specifically blockchain, offers a paradigm shift in document integrity. By creating immutable, time-stamped records, blockchain ensures that once a financial document (or its hash) is recorded, it cannot be tampered with or altered without cryptographic detection. This level of verifiable transparency is invaluable for high-trust environments, complex multi-party transactions, and fulfilling stringent regulatory requirements like those related to Know Your Customer (KYC) and Anti-Money Laundering (AML).

The Future is Integrated and Secure

For businesses aiming to remain competitive, adopting these digital finance documentation trends is non-negotiable. The future of finance documentation is integrated, highly automated, and secured by advanced technologies like AI and blockchain. Investing in these digital solutions now ensures compliance, operational efficiency, and a powerful foundation for scalable growth.

Tagged : / / / / / / / / /

Mastering the Cash Flow: The Complete Financial Document Cycle From Quotation to Receipt

Mastering the Cash Flow: An Introduction

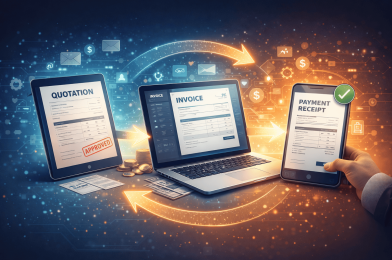
In the world of business finance, efficiency hinges on precision. The ‘Financial Document Cycle’ is the structured pathway that transforms a simple interest into realized revenue. Understanding this complete cycle—from the preliminary quotation to the final receipt—is crucial for maintaining healthy cash flow, ensuring regulatory compliance, and building strong client relationships.

Stage 1: The Initial Promise (Quotation and Estimate)

The journey begins with the quotation (or estimate). This document is not a binding agreement, but rather a formal proposal outlining the anticipated cost of goods or services. Key components include line-item details, project scope, and validity dates. It sets the baseline expectations for the transaction. A well-prepared quotation minimizes future disputes and signals professional intent, serving as the first formal step in the entire financial document cycle.

Stage 2: Formalizing the Agreement (Orders and Confirmations)

Once the client accepts the quotation, the transaction moves into the commitment phase. This often involves a Purchase Order (PO) issued by the buyer, detailing the exact items and quantities they wish to procure. On the seller’s side, a corresponding Sales Order (SO) confirms the commitment to deliver. These order documents replace the non-binding quote with a legal commitment, acting as internal documentation that greenlights inventory processing or service deployment.

Stage 3: The Call for Payment (Invoicing)

The invoice is perhaps the most critical document in the cycle. Issued after the goods or services have been delivered or rendered, it is the formal request for payment. A high-quality invoice must contain specific information: unique invoice numbers, clear payment terms (e.g., Net 30), due dates, and detailed breakdown of costs referencing the initial PO or SO. Timely and accurate invoicing is paramount to accelerating accounts receivable and optimizing the overall financial document cycle. Errors here often lead to delayed payment and friction.

Stage 4: Transaction Closure (The Receipt and Reconciliation)

The cycle concludes with the receipt. The receipt is the definitive proof of payment, confirming that the customer has fulfilled their monetary obligation. It serves as confirmation for the customer and is vital for the seller’s financial reconciliation process. Generating and archiving receipts efficiently is essential for tax purposes and accurate ledger balancing. Once the receipt is issued, the revenue is officially recognized, and the transaction is closed.

The Power of Automation in the Document Cycle

Managing this complex flow manually is resource-intensive and prone to human error. Modern businesses leverage ERP and accounting software to automate document generation, tracking, and compliance. Automation ensures that data seamlessly flows from the initial quote into the final receipt, drastically reducing processing time and improving data integrity across every stage of the financial document cycle. Mastering these four stages through strategic automation is the key to scalable financial success and robust cash flow management.

Tagged : / / / / / / / /

Why Payment Receipts Are the Unsung Heroes of Accurate Financial Reporting

The Crucial Link Between Receipts and Reporting Integrity

In the world of finance, precision is paramount. While many businesses view payment receipts merely as necessary paperwork, these small slips of evidence are, in fact, the bedrock upon which accurate financial reporting is built. Receipts transform estimated expenditures into verifiable data points, ensuring that a company’s financial statements reflect economic reality. Without a robust system for capturing and categorizing every receipt, a company risks fundamental flaws in its budgeting, tax compliance, and overall financial health.

Foundation of Verifiable Expense Tracking

For any expense to be legitimately recorded in the general ledger, it must be supported by adequate documentation. A payment receipt serves as this primary source document, detailing key information such as the vendor, the date, the specific item or service purchased, and the amount paid. This level of detail is critical for accurate categorization—is the expense classified as supplies, travel, or capital expenditure? Misclassification due to lack of proof can dramatically skew profitability ratios and budget tracking, rendering management reports unreliable for strategic decision-making.

Ensuring Audit Readiness and Regulatory Compliance

Perhaps the most critical role of payment receipts is their function in compliance and audit defense. Regulatory bodies, whether internal or external auditors, require verifiable evidence to substantiate every transaction claimed by the business. For instance, tax authorities demand receipts to validate business deductions. Without them, claimed expenses are likely to be disallowed, leading to costly penalties and fines. By consistently maintaining clear and comprehensive receipt records, companies demonstrate adherence to financial standards like Generally Accepted Accounting Principles (GAAP) or International Financial Reporting Standards (IFRS). This meticulous record-keeping significantly mitigates risk during a formal audit, proving the legitimacy of cash flows and expense reimbursements.

Streamlining Reconciliation and Reducing Financial Fraud

Receipts are essential tools in the month-end reconciliation process. When reconciling bank statements or credit card charges, matching every line item with a corresponding receipt ensures that no duplicate entries exist and that all transactions are accurately accounted for. This control mechanism is vital for expense management and curbing internal fraud. Requiring verifiable receipts for all employee expense reports establishes transparency and accountability, making it much harder for fraudulent or personal expenditures to be mistakenly or deliberately included in business financials. When receipts are missing or incomplete, the door is open for errors and unethical practices to undermine the integrity of the books.

The Digital Future of Receipt Management

Modern technology has revolutionized the traditionally cumbersome process of receipt management. Digital receipt capture via mobile apps, integrated expense software, and OCR technology ensures that documentation is preserved immediately, categorized accurately, and linked directly to the accounting software. This automation not only saves time but drastically reduces the incidence of lost receipts and human error. By embracing digital receipt management, businesses enhance the speed and accuracy of their financial reporting, transforming a burdensome administrative task into a powerful engine for reliable financial data.

Tagged : / / / / / / / / /

Securely Storing Payment Receipts: Essential Best Practices for Business Compliance and Data Protection

Why Secure Receipt Storage is Non-Negotiable

For businesses of all sizes, payment receipts are more than just proof of transaction; they are critical documents containing sensitive financial and customer data. Neglecting proper storage protocols exposes your business to severe risks, including massive fines under regulations like PCI DSS (Payment Card Industry Data Security Standard), data breaches, and significant loss of customer trust. Implementing a comprehensive strategy for securely storing payment receipts is not optional—it is a mandatory pillar of modern business compliance and data protection.

Understanding Legal and Compliance Requirements

The first step in securing payment data is understanding your legal obligations. PCI DSS mandates strict rules regarding the handling of cardholder data. Crucially, businesses should never store the full Primary Account Number (PAN), card verification values (CVV), or the PIN. Receipts, both digital and physical, must mask or truncate card numbers effectively. Beyond financial regulation, tax authorities often require businesses to retain receipts for audit purposes, typically ranging from three to seven years, depending on jurisdiction. Your storage system must therefore balance security with efficient retrieval for auditing.

Best Practices for Digital Receipt Storage

The majority of modern businesses utilize digital record-keeping, which offers efficiency but requires robust cybersecurity measures. To securely store digital receipts:

  • **Encryption is Key:** All stored receipt files must be protected using strong, industry-standard encryption (such as AES-256), both while at rest (on servers) and in transit (when accessed).
  • **Implement Access Controls:** Utilize the principle of least privilege. Only employees who absolutely require access to receipt data for their roles (e.g., accounting) should be granted permission. Access should be monitored via audit logs.
  • **Utilize Secure Cloud Services:** If using cloud storage, ensure the provider is compliant with relevant security standards (e.g., ISO 27001) and offers advanced features like Multi-Factor Authentication (MFA) and geo-redundancy for disaster recovery.
  • **Regular Backups:** Encrypted backups should be performed regularly and tested to ensure data can be recovered quickly in case of system failure or ransomware attack.

Managing and Destroying Physical Receipts

While digital storage dominates, physical paper receipts still exist and pose unique security challenges. They must be treated with the same level of security as digital files. Store paper receipts in locked, fireproof filing cabinets accessible only to authorized personnel. When the required retention period expires, secure destruction is paramount. Do not simply throw them away; use a cross-cut shredder that meets security standards, or hire a certified document destruction service.

Establishing Clear Retention and Destruction Policies

A formalized retention policy is essential. This policy must clearly define:

  1. How long each type of receipt must be kept, based on regulatory minimums.
  2. The secure procedure for data destruction (e.g., automated deletion for digital files; certified shredding for physical copies).
  3. The required documentation proving that destruction occurred securely and completely.

By proactively implementing these detailed best practices, businesses can move beyond mere compliance, enhancing operational security and safeguarding their reputation against the ever-present threat of data compromise.

Tagged : / / / / / /

Quotation vs Invoice: Understanding the Key Differences for Business Success

In the world of business finance, clarity is crucial. Two documents frequently used to outline costs and manage transactions are the quotation and the invoice. While both involve pricing, they serve vastly different legal and operational purposes. Misunderstanding their roles can lead to serious accounting errors, delayed payments, and even legal disputes. Mastering the distinction between a quotation and an invoice is essential for seamless business operations and healthy cash flow.

What is a Quotation? The Binding Offer

A quotation (or quote) is a formal document provided by a supplier to a potential client, detailing the exact cost for specific goods or services under defined conditions. Unlike a casual estimate, a quotation is typically legally binding. Once the client accepts the quote, the supplier is obligated to provide the specified work or product at the quoted price, often for a set duration (e.g., 30 days).

The primary purpose of a quotation is pre-sales. It helps clients budget accurately and compare prices before committing to a purchase. Key elements include the scope of work, itemized costs, payment terms (if accepted), and the validity period. It is a proactive step that formalizes the proposed transaction details.

What is an Invoice? The Demand for Payment

An invoice, conversely, is a legally enforceable document issued after the goods or services have been delivered or rendered. Its purpose is to officially request payment from the buyer for the completed work. The issuance of an invoice transforms the verbal or contractual agreement (often established by the accepted quotation) into a formal financial transaction requiring settlement.

An invoice must contain specific details for tax and accounting purposes, including a unique invoice number, the date of issue, the due date for payment, detailed breakdown of items delivered, and applicable tax (VAT/Sales Tax). It serves as the official record of the sale for both parties’ accounting ledgers and is crucial for accounts receivable tracking.

Key Differences Summarized

The most significant differences lie in timing, purpose, and legal status:

  • Timing: A quotation is sent before a sale agreement to propose a price. An invoice is sent after the fulfillment of the contract to demand payment.
  • Purpose: A quote is used for pricing and setting client expectations. An invoice is used for billing, tracking accounts receivable, and confirming revenue.
  • Legal Status: A quotation, once accepted, forms the basis of the contract (a binding promise of price). An invoice is the formal request for settlement based on that fulfilled contract (a binding liability).
  • Flexibility: Quotations offer fixed pricing that limits supplier changes unless the scope changes. Invoices reflect the final, non-negotiable amount due.

Why Does the Distinction Matter for Your Business?

For small businesses and freelancers, confusing these documents can create major financial headaches:

Accounting Accuracy: Invoices are revenue documents tracked in accounts receivable, directly impacting tax liabilities and income statements. Quotations are only potential sales and should not enter the revenue stream until accepted and fulfilled. Using a quote as a payment request severely confuses accounting software and audit trails.

Legal Protection: If a dispute arises over pricing, the accepted quotation acts as proof of the agreed-upon cost. If a dispute arises over non-payment, the invoice acts as legal evidence that the service was delivered and payment is owed. In essence, the quotation is the promise, and the invoice is the proof of fulfillment and the demand for remuneration. Understanding which document to use and when to send it is paramount for maintaining professional standards and ensuring prompt, accurate payment collection.

Tagged : / / / / / / / /