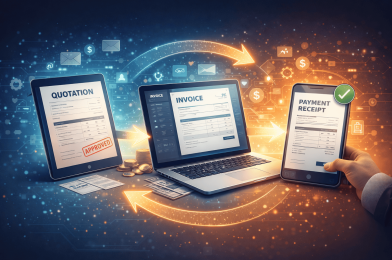
Avoid Payment Delays: 5 Common Invoicing Mistakes and How to Fix Them

Timely cash flow is the lifeblood of any successful business. Yet, countless payments are delayed not due to client unwillingness, but simple, avoidable invoicing mistakes. These errors create friction, require rework, and ultimately harm your financial stability. Identifying and fixing these common flaws is crucial for robust financial health and ensuring you get paid on time.

The Cardinal Sin: Missing or Incorrect Information

The single most frequent reason for an invoice being rejected or kicked back is incomplete data. Ensure every invoice meticulously includes:

  • Your full company name, tax ID (if required), and contact details.
  • The client’s legal business name and address.
  • A unique, sequential invoice number and the precise issue date.
  • Crucially, if working with large organizations, always include the correct Purchase Order (PO) number. Omitting the PO number is an instant payment block for many Accounts Payable (AP) departments, regardless of the services rendered.

Furthermore, avoid vague descriptions. Instead of listing “Consulting services,” specify: “Project X: Scope Definition and Q3 Marketing Strategy Review (15 hours).” Clarity minimizes internal questioning by the client’s team, ensuring faster approval.

Calculation Errors and Ambiguous Terms

While modern accounting software mitigates many mathematical errors, complex multi-rate projects or manual adjustments can still lead to miscalculations. Double-check all unit prices, quantities, taxes, and totals before sending. Even a small dollar difference can require a complete invoice reissue, delaying payment by days.

Equally critical is the lack of clear payment terms. Terms must be explicitly stated (e.g., “Net 30,” “Due Upon Receipt”). If late fees or interest rates apply, they must also be detailed upfront in your service agreement and referenced on the invoice to encourage promptness and ensure legal enforceability.

Sending Invoices to the Wrong Person

Many freelancers and small businesses mistakenly send invoices to the primary project contact (e.g., the marketing manager) instead of the Accounts Payable (AP) department or the designated finance email address. The invoice then sits in an inbox, awaiting manual forwarding, adding days or weeks to the payment cycle.

Always confirm the dedicated payment submission procedure during client onboarding. Ask this specific question: “Who is the designated AP contact, and what is the preferred submission method (direct email, dedicated portal upload, or mail)?” Direct submission bypasses internal bureaucracy.

Ignoring Follow-Up and Reconciliation

Even a perfectly generated invoice needs tracking. Many businesses lose track of cash flow because they lack a systematic process for monitoring payment due dates and chasing overdue accounts. Implement a simple system—whether spreadsheet-based or automated software—that flags invoices reaching 7 days overdue, 15 days overdue, and 30 days overdue.

A polite, professional automated reminder email is highly effective. Often, an overdue payment is simply an oversight, and a timely reminder resolves the issue quickly without straining the client relationship.

Conclusion: Standardize for Success

Prompt payment is a two-way street. By standardizing your invoicing process, meticulously eliminating common informational and calculation errors, and ensuring correct submission to the right contact, you drastically reduce friction. Investing a few extra minutes in accuracy today guarantees your business receives the cash flow it needs tomorrow.
Tagged : / / / / / /

Receipt Management Best Practices for Tax and Compliance: Essential Strategies

Introduction: Why Receipt Management Matters More Than Ever

In the complex world of finance, receipts are not merely slips of paper; they are critical evidence supporting every business deduction, transaction, and expense report. For businesses striving for tax efficiency and compliance, poor receipt management is a major liability leading to disallowed deductions, fines, and grueling audits. Implementing robust Receipt Management Best Practices is no longer optional—it is fundamental to financial health.

Digitalization is Non-Negotiable

The days of shoeboxes filled with paper receipts are over. The modern best practice dictates immediate digitalization. Utilizing high-quality mobile scanning apps or dedicated expense management software allows employees to capture receipts instantly, often while standing at the point of sale. Digital receipts should be stored as searchable PDFs or high-resolution images, preserving all key details—vendor name, date, total amount, and itemized purchase breakdown. This practice significantly reduces the risk of loss, fading, or destruction inherent to paper records.

Structuring for Swift Retrieval and Audit Readiness

Digital storage is only effective if it’s organized. Best practices require a consistent classification system. Receipts should be tagged and categorized according to expense type (e.g., travel, meals, supplies), employee, department, and relevant project or client. Centralized, cloud-based storage ensures that all necessary documentation is accessible instantly during an internal review or a tax audit. Automation tools featuring Optical Character Recognition (OCR) technology dramatically speed up this process by extracting data directly from the receipt image and matching it to transaction records.

Understanding Storage Duration and Legal Compliance

A common pitfall is misunderstanding how long receipts must be retained. While the IRS generally requires keeping documentation for three years from the date you filed the original return, some situations (such as substantial understatement of income) demand retention for up to six years. For capital assets, documentation must be kept for three years after the asset is sold or disposed of. Best practices recommend setting automated retention policies within your management system to ensure compliance across all jurisdiction requirements, often defaulting to seven years for maximum safety.

Implementing Clear Policies and Employee Enforcement

Effective receipt management starts with clear internal policies. Businesses must define what constitutes an acceptable receipt, acceptable spending limits, and the mandatory time frame for submission (e.g., 48 hours after the expense occurred). Regular training ensures employee adherence. Furthermore, compliance systems should automatically flag receipts missing necessary information or submitted past the deadline, fostering accountability and reducing manual review workload for the finance department.

The Advantage of Modern Expense Management Software

For organizations looking to optimize Receipt Management Best Practices, dedicated software offers the most streamlined solution. These platforms integrate receipt capture, categorization, policy enforcement, and reporting into a single system. By automating the reconciliation process, they minimize human error, ensure adherence to tax regulations, and provide real-time insights into expenditure, transforming a compliance chore into a strategic financial function.

Tagged : / / / / / / /

7 Costly Pricing Errors in Quotations: How to Save Your Business Money

The High Cost of Pricing Errors in Quotations

For any business, the quotation process is the crucial bridge between effort and revenue. However, sloppy preparation or rushed calculations can transform potential profit into realized loss. Common pricing errors in quotations are silent profit killers, eroding margins before a project even begins. Understanding these pitfalls is the first step toward tighter financial control and sustainable profitability.

Error 1: Failing to Account for Hidden Overheads

Many businesses focus solely on direct costs (materials, specific labor) while neglecting the true cost of doing business. Overheads like rent, utilities, insurance, software subscriptions, and administrative salaries must be allocated accurately across projects. If your pricing structure doesn’t factor in a realistic percentage for these ‘hidden’ costs, every job you win may actually be subsidized by your company’s core capital.

Error 2: Reliance on Outdated Cost Data

In today’s volatile economic climate, material and supply chain costs can fluctuate weekly. Using cost sheets that are more than 30 days old is a major risk. An outdated quote could easily undervalue required materials or fail to capture recent tariff increases, leading to significant margin compression when procurement occurs. Automated updates and integrated inventory systems are essential to combat this widespread issue.

Error 3: The Discounting Dilemma

While strategic discounting can secure high-value contracts, offering arbitrary or excessive discounts without understanding the true break-even point is dangerous. Sales teams often feel pressured to secure the deal and may give away too much margin. Implement strict discount ceilings tied directly to profit margin analysis. If a discount is granted, the justification must be clearly documented to ensure the overall profitability of the project remains viable.

Error 4: Miscalculating Labor and Time

Labor is often the most complex variable. Quotation errors frequently occur when businesses underestimate the time needed for project management, quality assurance, or unforeseen delays. Furthermore, calculating labor costs based only on salary, rather than the fully loaded cost (including benefits, taxes, and overhead allocation), results in an artificially low price that fails to cover actual expenditure.

Error 5: Lack of System Integration

Using disparate systems—spreadsheet pricing, separate CRM, and distinct accounting software—is a recipe for error. Manual data entry invites transposition mistakes, misinterpretations of scope, and inconsistencies between what was quoted and what was invoiced. Integrated CPQ (Configure, Price, Quote) software can eliminate these manual touchpoints, ensuring consistency and accuracy across the entire sales cycle.

Implementing a Robust Review Process

Protecting your company from these pricing errors in quotations requires more than just careful calculation; it demands a process. All high-value quotations should undergo a mandatory two-step review: first by the preparer for technical accuracy, and second by a financial controller or senior manager for margin analysis and adherence to pricing policy. This dual-check system prevents individual mistakes from becoming company losses.

Protecting Your Profit Margins

The success of your business hinges on the accuracy of your quotes. By proactively addressing hidden costs, updating data, and implementing systematic controls, you can stop the silent leak of capital. Investing time in robust pricing processes today guarantees healthier profit margins tomorrow.

Tagged : / / / / / / /

The Indisputable Legal Importance of Payment Receipts in Business Audits

The Unsung Hero of Business Compliance

In the complex world of finance and taxation, businesses often focus heavily on profit margins and strategic growth, overlooking a crucial component of fiscal integrity: the humble payment receipt. Far from being mere scraps of paper, payment receipts are legally binding documents that serve as the bedrock of financial accountability. Their meticulous management is not just an administrative task, but a vital defensive strategy against potential scrutiny. For any business facing an internal review or an official tax audit, these records transition from administrative necessity to indisputable proof of legitimate business activity.

Legal Mandates: Why Receipts Are Non-Negotiable

Regulatory bodies, such as the Internal Revenue Service (IRS) in the US, demand comprehensive documentation to validate every expense claimed. If a business cannot produce adequate substantiation, the expense is generally disallowed, leading to costly tax reassessments, penalties, and interest charges. Receipts are the primary evidence required to justify deductions for business expenses, travel, meals, and purchases of capital assets. They must contain specific details, including the date of the transaction, the amount paid, the vendor’s name, and a clear description of the goods or services procured. Without this proof, the entire financial narrative presented by the company during an audit collapses under questioning. This legal obligation extends beyond mere tax deduction; it supports compliance with anti-fraud regulations and financial transparency standards.

Navigating the Audit Storm: Proof of Transaction

During a business audit, the burden of proof rests squarely on the taxpayer. Auditors use payment receipts as a cross-referencing tool, matching them against ledger entries, bank statements, and internal purchase orders. A complete and organized archive of receipts provides undeniable proof of the transactional flow, significantly streamlining the audit process and reducing the likelihood of extended investigations. Conversely, missing or incomplete receipts are red flags, often signaling poor internal controls or potential irregularities that trigger deeper examination into the company’s books. Investing in robust receipt management software or processes is often far cheaper than facing the consequences of a disallowance.

Best Practices for Robust Record Keeping

Modern businesses must embrace efficient record-keeping practices. While physical receipts are still valid, transitioning to digital archiving systems offers superior security, organization, and retrieval speed. Digital receipts (scanned images or e-receipts) must be maintained in a manner that ensures their authenticity and integrity over time. Furthermore, businesses must adhere to strict retention schedules—typically mandated to be seven years from the date the tax return was filed—ensuring that even old records are available if prior years are called into question. Consistent, documented procedures for capturing, processing, and storing receipts are essential to demonstrate professionalism and compliance during an audit.

Conclusion: Safeguarding Your Business Future

The legal importance of payment receipts in business audits cannot be overstated. They are the objective evidence that validates a company’s financial health and adherence to legal standards. By treating receipt management as a critical component of risk mitigation and compliance strategy, businesses can confidently navigate audits, protect their financial standing, and ensure long-term stability.

Tagged : / / / / / /

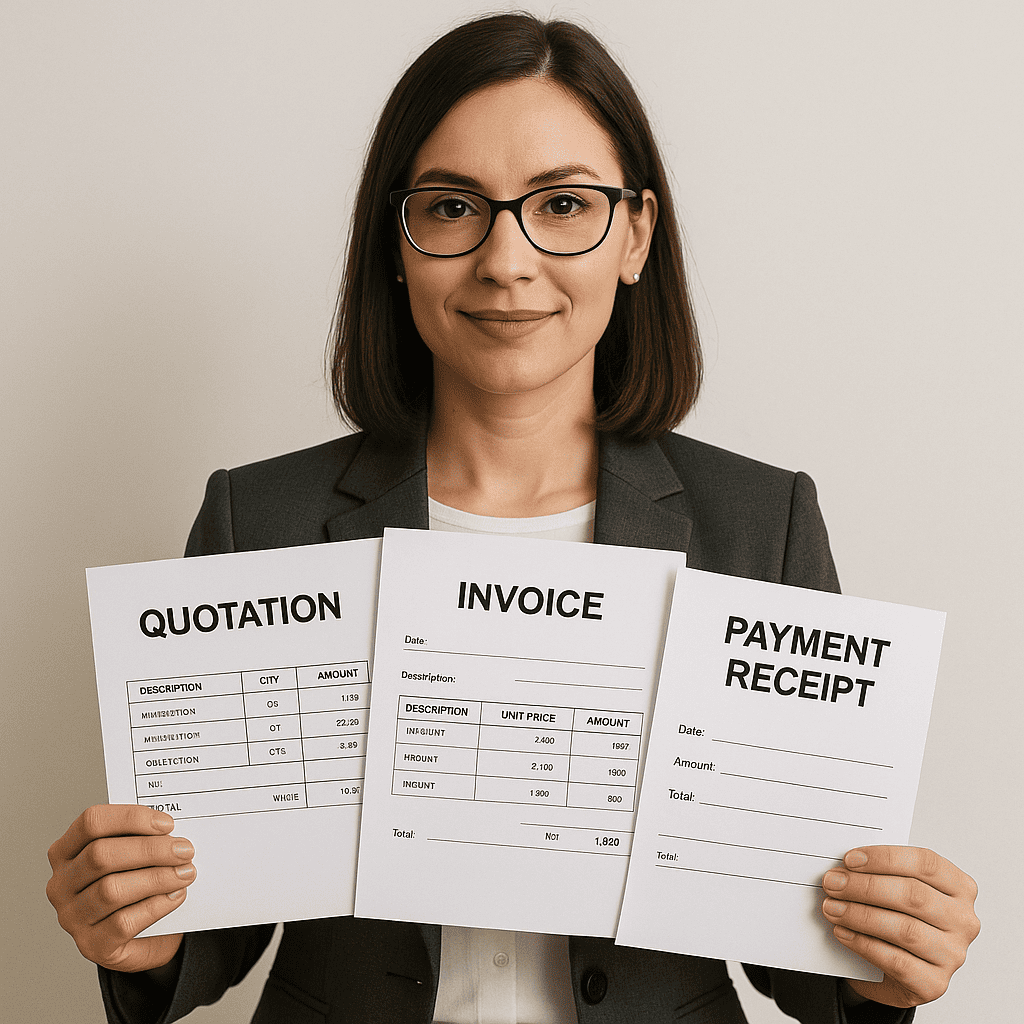
Mastering the Financial Document Cycle: From Quotation to Receipt

Introduction: The Engine of Business Finance

In the world of commerce, every transaction, whether big or small, follows a strict, interconnected series of steps known as the Financial Document Cycle. This cycle ensures clarity, accountability, and compliance, forming the backbone of effective accounts receivable and financial management. Understanding this complete journey—from the moment a customer expresses interest to the final confirmation of payment—is crucial for maximizing cash flow and minimizing disputes.

Stage 1: The Initial Offer (Quotation & Proposal)

The cycle begins with the Quotation. A quotation is a non-binding document outlining the cost of goods or services under specified terms. Once the customer accepts this quotation, it often transitions into a formal Sales Proposal. Accuracy at this stage is paramount, as the quoted price forms the basis for all subsequent financial documents.

Stage 2: Formalizing the Agreement (Sales Order & Delivery Note)

Upon acceptance, the quotation evolves into a Sales Order (SO). The SO is an internal document that confirms the details of the customer’s purchase, authorizing the internal teams (like inventory or production) to prepare the goods or services. Following the delivery, a Delivery Note is issued, confirming that the items reached the customer, often signed as proof of delivery. While not a demand for payment, these documents establish concrete proof that the goods were provided as agreed.

Stage 3: Requesting Payment (Invoicing)

The most critical document in the cycle is the Invoice. Issued after the goods or services have been delivered (or sometimes progressively, depending on contract terms), the invoice is a formal demand for payment. It clearly states the amount due, payment terms (e.g., Net 30), and methods of payment. Accurate, timely invoicing directly impacts cash flow. A well-structured invoice must reference the initial sales order and quotation for traceability.

Stage 4: Completing the Transaction (Receipt and Reconciliation)

The cycle concludes with the Receipt. Once the payment has been received and processed, the receipt is issued to the customer as proof that the outstanding balance has been cleared. Internally, this step involves bank reconciliation—matching the received funds with the issued invoice. This final confirmation closes the transaction, updates the accounts receivable ledger, and confirms the revenue for accounting purposes.

Conclusion: Streamlining for Success

While the steps are linear, manual processing often introduces errors and delays. Modern businesses leverage automated Enterprise Resource Planning (ERP) or specialized accounting software to seamlessly convert documents between stages, ensuring that the entire financial document cycle remains fast, accurate, and compliant. Mastering this cycle is not just about paperwork; it’s about efficient cash conversion and sustained business health.

Tagged : / / / / / / /

7 Costly Pricing Errors in Quotations Businesses Must Avoid to Protect Profit

The Staggering Price of Inaccurate Sales Quotes

For any business, the quotation process is the direct pathway to revenue. Yet, manual entry, outdated calculations, and systemic oversight lead to endemic quotation pricing errors that silently erode profitability. While a small mistake might seem insignificant, accumulated over hundreds of deals, these miscalculations can transition a healthy profit margin into a substantial loss. Identifying and correcting these pitfalls is not merely good practice—it’s essential financial hygiene.

Overlooking Overhead and Indirect Expenses

One of the most frequent and severe mistakes businesses make is basing quotes solely on direct costs (materials and labor). While these inputs are straightforward, neglecting indirect costs—such as utilities, administrative salaries, insurance, or specialized software licenses—is a guaranteed way to underprice your services. If your pricing structure doesn’t incorporate a justified allocation for overhead, every successful quote is actually setting you back financially. True profitability requires fully loaded costing.

Inaccurate or Outdated Cost Inputs

The speed of market change can rapidly turn accurate cost data into liabilities. Supply chain fluctuations, vendor price increases, and changes in material availability often mean that the cost sheet used last quarter is no longer valid today. Businesses relying on static spreadsheet templates rather than dynamic, real-time data systems are highly susceptible to this error, unknowingly quoting last year’s prices for this year’s expenses.

The Danger of Scope Creep and Underestimation

A firm quotation is based on defined specifications. However, in many service-based industries, project requirements evolve post-quote issuance—a phenomenon known as scope creep. If the initial quote does not include mechanisms (or buffers) to address expanded scope, the business ends up delivering significantly more value than compensated for. Clear contractual definitions and change order processes are vital defense mechanisms against this silent profit killer.

Mismanagement of Complex Discounts and Tiered Pricing

Offering tiered pricing or complex bulk discounts is a common sales tactic, but it is also a major source of quotation pricing errors. When sales representatives manually apply discount percentages or combine multiple promotional offers, the likelihood of arithmetic errors, or applying unapproved combinations, skyrockets. These mistakes are particularly difficult to track until financial reconciliation, often resulting in selling products below the intended profitability threshold.

Protecting Profit: Implementing Robust Processes

Preventing these costly errors requires moving beyond outdated methods. Standardization is key: using centralized, version-controlled templates and establishing rigorous review processes for high-value quotes. For larger organizations, investing in Configure, Price, Quote (CPQ) software can automate complex rules, ensure costs are always current, and instantly flag illogical pricing combinations. Auditing your quotation process regularly can save hundreds of thousands in lost revenue.

Tagged : / / / / / /

Why Real Time Invoice Tracking is the Non-Negotiable Key to Sustainable Business Growth

The Silent Threat to Growing Businesses: Delayed Payments

For any growing business, cash flow is king. Yet, the traditional methods of handling accounts receivable—relying on spreadsheets, manual reconciliation, and delayed reporting—create a dangerous lag. This lack of immediate visibility means business owners are often making crucial spending and investment decisions based on outdated information. This is why adopting Real Time Invoice Tracking is no longer a luxury, but a fundamental requirement for sustainable expansion.

The Lifeline of Cash Flow Management

The single greatest benefit of real time invoice tracking is its profound impact on liquidity. When you know the exact status of every outstanding invoice the moment it changes (from ‘sent’ to ‘viewed’ to ‘overdue’), you gain unparalleled control. This immediacy allows finance teams to predict upcoming dips or surpluses with accuracy. Instead of waiting weeks for end-of-month reporting, real time data enables proactive follow-up on overdue payments, drastically reducing your Days Sales Outstanding (DSO). By optimizing DSO, growing businesses can ensure they have the working capital necessary to seize new opportunities and manage operational costs without strain.

Minimizing Errors and Ensuring Compliance

Manual invoicing processes are ripe for human error—miscalculated totals, duplicated entries, or invoices sent to the wrong addresses. These mistakes don’t just cost money; they erode customer trust and complicate compliance efforts. Real Time Invoice Tracking systems automate validation and reconciliation, flagging discrepancies instantly. This accuracy is vital when scaling. Furthermore, automated tracking ensures a clear audit trail for every transaction, simplifying tax preparation and regulatory compliance, saving countless hours during audits.

Fueling Scalability Through Data and Efficiency

As a business grows, the volume of transactions multiplies. Relying on outdated systems quickly creates a bottleneck, forcing businesses to hire more administrative staff just to keep up with paperwork. Real Time Invoice Tracking is inherently scalable. It frees up your team from tedious data entry and tracking tasks, allowing them to focus on high-value activities like relationship building and strategic analysis. The real-time data provided by these systems is powerful: it identifies trends in payment behavior, highlights high-risk clients, and reveals opportunities to optimize pricing or payment terms. This strategic insight is critical for informed, data-driven decision-making.

Enhanced Customer Relationships and Professionalism

When a customer calls with a query about a recent bill, your response needs to be instant and accurate. Fumbling through files or promising to “call back later” reflects poorly on your professionalism. RTIT provides instant access to comprehensive billing history and current status updates. This transparency not only solves customer issues quickly but builds stronger, more professional relationships, making it easier to secure repeat business. In the competitive landscape, efficiency and clarity are key differentiators.

Conclusion: Embracing the Future of Finance

For businesses committed to growth, delay is costly. Implementing Real Time Invoice Tracking moves accounts receivable from a reactive headache to a proactive financial tool. It secures your cash flow, protects your compliance status, and provides the essential strategic data needed to navigate the challenges of scaling successfully. Investing in robust tracking technology is investing directly in your future profitability.

Tagged : / / / / / /

The Hidden Drain: Common Pricing Errors in Quotations That Cost Businesses Money

A sales quotation is more than just a list of prices; it is a legally binding promise that determines your business’s profitability. Yet, countless companies routinely suffer significant losses due to overlooked or poorly calculated elements in their final quotes. Understanding the most common pricing errors in quotations is the first critical step toward safeguarding your bottom line.

The Silent Killer: Scope Creep and Ambiguity

One of the most insidious threats to profitability is scope creep. This occurs when the client gradually expands the project requirements or requests additional features not detailed in the original quotation—without an associated adjustment to the price. Businesses often fail to establish clear boundaries and rigorous change management processes. An ambiguous quote leaves too much room for interpretation, leading the client to assume certain deliverables are included when they are not, forcing the vendor to absorb the extra cost.

Neglecting Hidden Costs and Overheads

Many businesses, particularly smaller enterprises, focus solely on direct material and labor costs, forgetting the essential—but less visible—expenses required to keep the lights on. Hidden costs include administrative overhead, utilities, depreciation of equipment, insurance, and quality assurance time. Failing to adequately factor these overheads into your hourly rates or project fees means that every successful quote, while generating revenue, is silently eroding your overall profit margin. Your quote must reflect the true cost of doing business, not just the cost of fulfilling the order.

The Danger of Manual Calculation Errors

In the digital age, relying on complex spreadsheets or manual calculators remains a significant source of inaccurate pricing. Human error is unavoidable: a misplaced decimal, a simple transposition, or an outdated formula can instantly transform a profitable project into a loss leader. Consistent pricing demands standardized formulas, real-time data integration, and, ideally, dedicated quoting software that automates calculations and ensures consistency across all sales personnel.

Miscalculating Labor and Project Duration

Underestimating the time required for a task is a universal quoting mistake. This error often stems from optimism bias, where project managers assume perfect conditions or fail to account for inevitable delays, rework, or non-billable administrative time. Furthermore, labor costs must accurately reflect not just the employee’s salary, but also their burden rate—including taxes, benefits, training, and paid time off. Ignoring the full burdened cost of labor severely diminishes realized margins.

Ignoring Input Cost Fluctuations

For businesses dealing with commodities, raw materials, or globally sourced components, input costs can change rapidly. A quotation issued today, based on last month’s material price list, might be fundamentally flawed if the sales cycle is long. Effective businesses implement a system for rapid price list updates and, crucially, include clear expiration dates and material cost clauses in their quotations to protect against market volatility during the negotiation period.

The Fix: Implementing Accuracy and Review

To mitigate these costly pricing errors in quotations, businesses must adopt rigorous internal standards. Implement a mandatory peer review process for all high-value quotes. Invest in quoting and configuration (CPQ) software that centralizes pricing rules, integrates with inventory systems, and ensures every variable—from freight costs to required margin—is accounted for before the quote reaches the client. Prioritizing precision in your quoting process is not merely a task; it is a fundamental strategy for sustainable growth and profit preservation.

Tagged : / / / / / /

Precision Pays: How Automation Is Reducing Financial Errors Across Businesses

The Dawn of Error-Free Finance

In the past, financial operations were synonymous with stacks of paperwork, complex spreadsheets, and the inevitable risk of human error. Even the most diligent employees could misplace a decimal, transpose numbers, or miss a key reconciliation item. These errors, though small individually, accumulate into significant financial losses and compliance headaches for businesses of all sizes. Today, however, a seismic shift is underway: automation is stepping in to guarantee precision where human fallibility once reigned supreme. The integration of advanced technological solutions is fundamentally redefining the role of the finance department, moving it from a reactive record-keeper to a proactive, reliable strategic partner.

Eliminating Manual Data Entry Risk with RPA

The core challenge in finance is data integrity. Manual data entry—whether inputting thousands of invoices, processing employee expenses, or calculating complex multi-jurisdictional payroll—is the primary bottleneck and the leading source of errors. Robotic Process Automation (RPA) tools have emerged as true game-changers. These software ‘bots’ mimic human actions to handle repetitive, rule-based tasks with perfect consistency, twenty-four hours a day. By automating high-volume tasks like three-way matching for accounts payable and performing daily bank reconciliations, businesses ensure that data is entered, verified, and reconciled identically every single time. This drastic reduction in manual handling not only saves countless hours but fundamentally eradicates the risk associated with fatigue, distraction, or simple oversight, delivering immediate and measurable ROI.

Advanced Tools: AI, Machine Learning, and Verification

Modern financial automation extends far beyond simple RPA. Advanced technologies like Artificial Intelligence (AI) and Machine Learning (ML) are deployed to handle more complex, cognitive scenarios previously requiring human judgment. For instance, AI-powered systems can automatically categorize nuanced transactions, extract data from varied document formats (such as non-standard invoices), and continuously monitor financial flows to flag unusual spending patterns for immediate fraud detection. ML algorithms are particularly adept at identifying anomalies and predicting potential compliance breaches before they occur. Furthermore, automated workflow systems ensure that every step of the approval process, from budget allocation to vendor payment, is standardized, documented, and enforced. This robust system eliminates the potential for unauthorized transactions or missed sign-offs that frequently result in audit failures and significant penalties.

The Strategic Advantages of Automated Finance

While error reduction is the most immediate and tangible benefit, the strategic implications of financial automation are profound and transformative. First, accuracy leads directly to flawless regulatory compliance. Automated systems inherently create detailed, time-stamped audit trails for every transaction, simplifying adherence to complex standards like GAAP, IFRS, and GDPR. This capability significantly reduces the burden and risk associated with external audits. Second, the speed of automated processes—allowing the closing of financial books in days instead of weeks—provides decision-makers with timely, reliable data. This enables superior forecasting, proactive financial planning, and rapid response to market shifts. Finally, and perhaps most importantly, by freeing up skilled finance professionals from mundane data scrubbing and error checking, companies can refocus their teams on higher-value activities, such as strategic analysis, complex modeling, and business partnership. Embracing automation is no longer a luxury; it is the definitive operational imperative for achieving financial reliability, cutting costs, and securing a competitive advantage in the data-driven world.

Tagged : / / / / / /

Mastering the Financial Document Cycle: From Quotation to Final Receipt

Mastering the Financial Document Cycle

For any business, maintaining healthy cash flow and accurate records hinges on a seamless flow of financial documentation. The complete financial document cycle, spanning from the initial customer inquiry to the final receipt, is a critical operational process. Understanding and optimizing this cycle not only ensures compliance but also accelerates payment times and reduces administrative overhead.

Phase 1: Initiation – Quotation and Proposal

The cycle begins with the customer’s request. Your response is the Quotation or Estimate. This document details the products, services, costs, terms, and delivery schedules. It is a non-binding offer, setting expectations for the transaction. If the customer agrees, the quotation transforms into a formalized commitment. In B2B environments, this commitment often takes the form of a Sales Order or a Purchase Order (PO) issued by the buyer, which legally binds both parties to the agreed-upon terms and prices.

Phase 2: Execution – Invoicing and Tracking

Once the goods or services have been delivered, the process moves to billing. The Invoice is the official demand for payment. A high-quality invoice must clearly reference the original sales order or PO number, detail the items delivered, the total amount due, payment terms (e.g., Net 30), and the due date. Timely and accurate invoicing is crucial for minimizing Days Sales Outstanding (DSO).

During this phase, robust document management is essential. Businesses must meticulously track outstanding invoices, often utilizing accounts receivable software. Automated reminders and clear internal processes prevent invoices from slipping through the cracks, a common source of cash flow problems. This tracking ensures that the financial document cycle remains on schedule.

Phase 3: Completion – Payment and Receipt Generation

The cycle reaches its conclusion upon payment. As soon as funds are received—whether via bank transfer, credit card, or check—they must be accurately reconciled against the open invoice. The final step is issuing the Receipt. The receipt is proof that the debt has been fully settled and officially closes the transaction in the financial records.

A proper receipt should include the date of payment, method of payment, amount received, and a reference to the original invoice number. Electronically generated receipts are now standard practice, offering instant delivery and further bolstering the efficiency of the financial document cycle.

Optimizing Your Workflow

To truly master the financial document cycle, businesses should focus on automation. Implementing integrated Enterprise Resource Planning (ERP) or accounting systems allows documents to seamlessly flow from one stage to the next—converting a quotation directly into an invoice and then generating a receipt upon payment recording. This integration minimizes manual entry errors, accelerates processing speed, and provides real-time visibility into the health of your accounts receivable, ensuring optimal performance from quotation to final receipt.

Tagged : / / / / / / /